

RedotPay: Crypto Card & Pay
by Red Dot Technology Limited
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
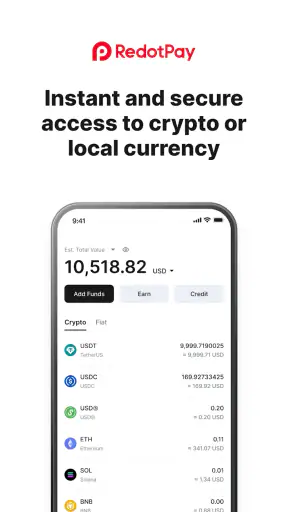
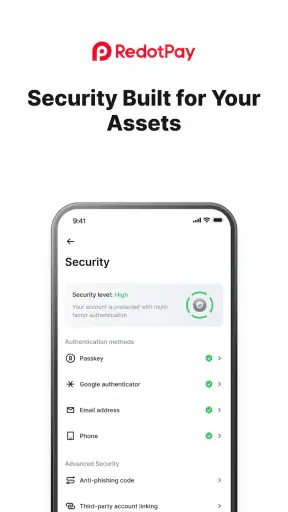
 Analysis by Getfullapps
I approached RedotPay as a practical finance app rather than as a simple crypto showcase. Its central promise is straightforward: make digital assets usable in everyday spending, while also giving you a place to hold, swap, and send them. That sounds convenient, but the real question is whether it fits the way you already manage money. In my experience, the answer depends less on how interested you are in cryptocurrency and more on whether you value payment flexibility over the predictability of a traditional bank account.
Developed by Red Dot Technology Limited, this free finance app is aimed at people who want to use crypto beyond an exchange screen. It has an Everyone content rating, works on Android devices running version 7.0 or later, and its current release is 3.13.2. The app has built a sizeable audience, with more than five million installs, a 4.4 average from roughly seventy-three thousand ratings, and about one thousand three hundred written reviews. Those figures suggest that the idea is reaching ordinary users, not only experienced traders.
I would not describe it as a replacement for every banking app or every crypto exchange. It occupies a more specific space between the two. You get a wallet-oriented experience, tools for swapping and sending digital assets, and a way to spend crypto internationally. That combination is useful when your money already exists in crypto, but it is less compelling if you mainly need budgeting, bill management, savings accounts, or conventional financial services.
What to Decide Before Moving Your Spending to Crypto
Before I move any regular spending into a crypto-based payment routine, I decide which purchases genuinely benefit from it and which are better left to a bank card. I also think through how I’ll keep a backup available and review transfers without turning every purchase into extra bookkeeping. That distinction makes it easier to judge whether crypto spending can become a useful habit rather than a novelty.
Start with the job you want the app to perform
Before installing it, I would define the exact problem you want solved. Are you trying to pay while travelling, move crypto to another person, convert between assets, or keep a separate spending balance? These are different jobs, and the app makes the most sense when at least one of them is part of your normal routine.
If your goal is simply to buy and hold a digital asset, a conventional exchange may be easier to understand. If you want a familiar current account, a bank app is usually the more natural choice. RedotPay becomes more interesting when the starting point is crypto and the destination is real-world spending. That direction matters: it is designed around making crypto more usable, not around hiding the fact that crypto is involved.
I also think about how often I need to move money. Someone who makes one occasional crypto purchase may find a dedicated wallet and a separate payment method less confusing. Someone who receives crypto, swaps between assets, sends funds to contacts, and wants to spend from the same general setup may appreciate having those actions close together.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Convenience does not remove the need for checking
A wallet that can be used for spending feels more immediate than a long-term investment account. That is helpful, but it also makes small mistakes more consequential. I would check the selected asset, destination, and amount before confirming any transfer. A payment-oriented design can encourage fast decisions, while crypto transactions still deserve slow attention.
My practical advice is to begin with a small test amount. I would first learn how the wallet is arranged, how swapping is presented, and how sending works before treating it as my main spending route. This is not a criticism unique to this app; it is the sensible habit whenever a financial tool combines custody, transfers, and payments.
The worldwide angle is useful, but not universal
The international spending focus is one of the strongest reasons to consider it. For a traveller or remote worker who already holds crypto, having a payment-focused route can be more convenient than repeatedly moving funds through several services. It may also reduce the mental gap between “money I own digitally” and “money I can actually use.”
Still, I would not assume that every merchant, country, asset, or transaction will feel identical. Real-world acceptance, conversion steps, and the behaviour of a payment can depend on circumstances outside the app itself. I would keep a conventional backup payment method when travelling. That is especially important if a purchase is urgent or if access to your crypto balance depends on connectivity, account access, or a particular transaction flow.
Who should think twice
I would be cautious about recommending it to a person who dislikes volatility or expects a bank-like experience. Crypto balances can change in value, and a wallet that supports swapping does not turn those assets into stable cash. Someone who needs predictable household budgeting may be better served by a traditional bank account and a separate crypto app.
I would also hesitate if you are uncomfortable being responsible for digital-asset decisions. The app can make actions feel more approachable, but it cannot remove the importance of understanding what you are sending or swapping. New users should not treat a smooth interface as permission to skip basic checks.
Where the app earns its place
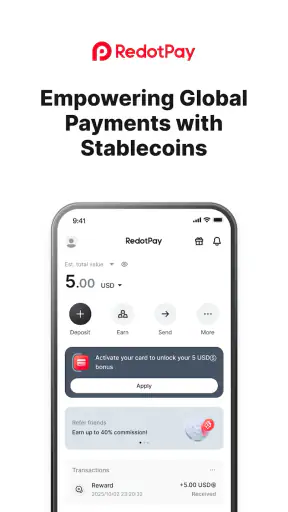
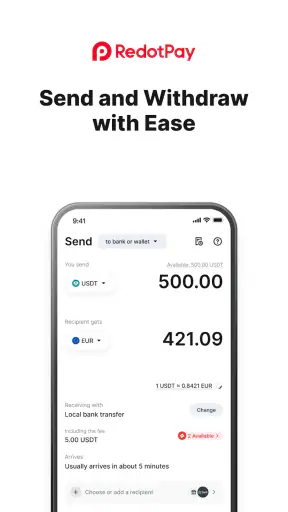
The clearest strength is the connection between holding and spending. Many crypto tools stop at trading or storage. RedotPay is more appealing when I want one crypto-oriented environment that reaches toward everyday payments. The wallet, swap, and send functions support different stages of the same workflow instead of forcing every action into a separate service.
That matters in a realistic situation. Imagine I am travelling and receive part of my income in crypto. I can keep a balance available for spending, move between assets when necessary, and send funds to another person without treating each task as an entirely different project. I still need to review each action, but the overall routine is easier to picture than a chain of unrelated apps.
Another useful quality is separation. I can think of this kind of app as a dedicated spending pocket rather than the place where all my finances must live. Keeping a limited amount for travel, online purchases, or crypto-related expenses can make the purpose clearer. It also helps me avoid mixing daily household money with an asset category that may behave differently from ordinary cash.
Three habits that make the experience safer and clearer
First, I would label the purpose of every transfer before making it. A payment to a friend, a move between my own wallets, and a swap are not interchangeable actions. Writing a short note outside the app or keeping a simple record can prevent confusion later, especially if several transactions happen close together.
Second, I would treat the swap screen as a decision point, not as a shortcut. Before confirming, I would review which asset is being exchanged and how much I intend to move. The convenience of having swapping beside spending is valuable, but it can also make an impulsive conversion feel like a routine tap.
Third, I would keep a backup plan for travel. The strongest use case for this app is also where preparation matters most. I would carry another payment option and avoid putting the entire trip budget into one digital route. This gives the app room to be useful without making it responsible for every essential purchase.
What the audience size tells me—and what it does not
The app’s adoption is reassuring in one limited sense: it is not an obscure experiment that only a handful of people have tried. The combination of over five million installs and a 4.4 average indicates meaningful interest and generally positive reception. I see that as a reason to investigate it, not as proof that it will suit every financial situation.
Ratings cannot tell me whether a particular payment route works well in my country, whether the wallet matches my preferred assets, or whether the workflow is comfortable for my personal habits. Those are decisions I would make through a small trial, careful reading inside the app, and a clear understanding of what I am using it for.
Where a different category may be better
A traditional bank app is still the better fit for salary deposits, predictable bills, household budgeting, and familiar consumer protections. Its strengths are not the same as RedotPay’s. If I want to see my regular income and expenses in one conventional ledger, I would not move that job to a crypto wallet.
A dedicated exchange may be preferable for someone whose main interest is trading. Exchanges are typically built around market activity, order decisions, and asset management rather than daily spending. I would choose that category when buying or selling is the priority and payment convenience is secondary.
A basic self-custody wallet may suit a user who wants direct control and minimal extras. RedotPay’s broader purpose is attractive precisely because it connects several actions, but a person who wants a narrowly focused storage tool may prefer less functionality. More abilities can mean more decisions, and not everyone benefits from having spending, swapping, and sending nearby.
Finally, a conventional prepaid or travel payment product may be easier for someone who wants a fixed spending amount with no crypto exposure. It may offer a simpler mental model: load money, spend money, check the balance. RedotPay is the more relevant option when crypto ownership is already part of the plan, not when you are searching for the simplest possible travel card.
What switching actually involves
Moving to a new financial app is not only a matter of installing it. I would need to decide how much of my crypto activity belongs there, which wallet balance is for spending, and how I will track transfers and swaps. That setup work is modest compared with changing banks, but it is still real. The app is easiest to adopt when I give it a defined role from the beginning.
I would start by separating experimental use from essential use. A small spending balance lets me learn the interface without putting rent, travel-critical funds, or emergency money into an unfamiliar workflow. Once I understand how I personally use the wallet, I can decide whether it deserves a larger role.
There is also a record-keeping cost. If I move money between a bank, an exchange, a wallet, and a payment service, my financial history becomes more fragmented. RedotPay can simplify the crypto-to-spending path, but it does not automatically make every account, transaction, and personal budget part of one unified system. I would keep my own basic transaction notes, particularly if I regularly swap assets or send funds to several people.
The free price makes trying it less intimidating, but “free” should not be confused with “cost-free in every possible situation.” Financial actions can involve their own conditions, conversion details, or network-related considerations. I would inspect the amount and final result shown before confirming rather than assuming that the absence of an upfront app price means every action has the same outcome.
My recommendation for different kinds of users
I recommend giving RedotPay a serious look if you already hold crypto and want a more practical way to use it. It is especially suitable for someone who travels, sends digital assets, or wants a separate crypto spending balance instead of leaving everything inside a trading account. The combination of wallet access, swapping, sending, and international spending gives it a clear identity.
I would recommend a cautious trial rather than an immediate full switch. Install it, explore the main workflow, and use a small amount first. Pay attention to how easily you understand the balance, how confidently you can distinguish a swap from a transfer, and whether the spending process fits your normal routine. Those observations are more useful than relying on a rating alone.
I would skip it as a primary financial app if I do not own crypto, dislike asset volatility, or mainly need conventional banking tools. In those cases, a bank, prepaid travel product, or focused exchange is likely to create less friction. The app does not need to replace those categories to be useful; it simply needs to solve the crypto-spending problem well for the right person.
My final view is positive but deliberately measured. RedotPay makes sense because it tries to close a practical gap: digital assets are easy to discuss, but people also want a way to move and spend them. For me, its value comes from that bridge, not from treating it as an all-purpose bank. Use it as a defined crypto payment and wallet tool, keep a backup for important spending, and start small while you learn the workflow. With that approach, the app can be a convenient addition to a broader financial setup rather than a risky substitute for everything else.
Pros
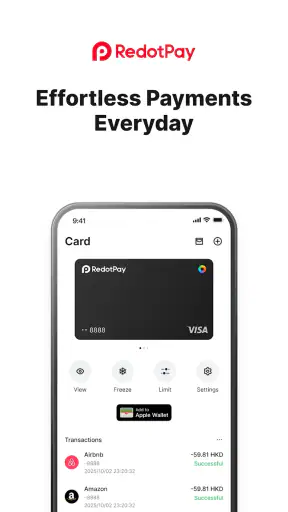
- Supports crypto-funded payments with a practical Visa card option.
- Offers virtual cards for online purchases without waiting for delivery.
- Provides in-app tracking for card spending and transaction activity.
- Can be useful for users who frequently move between crypto and fiat payments.
- Available on mobile, making account and card management convenient on the go.
Cons
- Availability and features may vary depending on your country and verification status.
- Crypto conversion rates and service fees can affect the final payment cost.
- Card usage may depend on merchant acceptance and regional Visa restrictions.
- Identity verification requires submitting personal information before full access.
- Crypto prices can change quickly, adding uncertainty to the value of held funds.
FAQs for RedotPay: Crypto Card & Pay
What is RedotPay: Crypto Card & Pay, and how does it work?
RedotPay is a crypto-focused payment app designed to let users manage digital assets and use them for everyday payments. Depending on availability in your country, the service may provide a virtual or physical payment card, crypto wallet functions, transfers, and merchant payments. Users typically add supported cryptocurrency, convert it when making a payment, and monitor transactions through the app. Features and supported assets can vary by region.
Can I use the RedotPay card for online and in-store purchases?
The RedotPay card is primarily intended for payments wherever the relevant card network is accepted, including many online stores and, where supported, physical point-of-sale terminals. However, acceptance is not guaranteed for every merchant, country, subscription service, or transaction category. Before relying on it for regular spending, check the current card availability, supported regions, merchant restrictions, and whether a physical card or compatible mobile wallet is required.
Which cryptocurrencies and fiat currencies does RedotPay support?
RedotPay supports selected cryptocurrencies and may offer conversion into a card settlement or spending currency, but the exact list can change over time. Availability may also depend on your location, account status, and product type. Before depositing funds, review the supported-asset list inside the app and confirm the correct network for transfers. Sending an unsupported token or using the wrong blockchain network can result in delayed or unrecoverable funds.
Are there fees, limits, or identity-verification requirements?
Users should expect RedotPay to apply certain conditions, such as identity verification, transaction limits, card issuance or delivery charges, conversion spreads, withdrawal fees, and possible network fees. The actual costs depend on the service and your jurisdiction, so they should be checked in the app before confirming a transaction. Verification may require personal information and documents, and some features may remain unavailable until the account review is completed.
Is RedotPay safe, and what should I do if my account or card is compromised?
RedotPay uses account-security measures such as login protection, transaction controls, and verification procedures, but no financial app is completely risk-free. Protect your password, enable available two-factor authentication, avoid sharing recovery or verification codes, and download the app only from an official store. If you notice an unfamiliar login, transfer, or card payment, immediately freeze the card or account through the app and contact official customer support.

RedotPay: Crypto Card & Pay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@redotpay.com, visit https://www.redotpay.com, or review their http://www.redotpay.com/privacy/.










